The Central Bank has approved a national strategy for the development of financial technology for 2026-2030. Its main goal is to make the country the most attractive jurisdiction in Central Asia for fintech companies by the end of 2030, while expanding individuals' and businesses' access to secure digital financial services.
The strategy will be implemented in three stages. In 2026-2027, the plan is to build the basic infrastructure of the fintech market. In 2028-2029, authorities aim to launch open banking, expand digital identification and integrate payment systems. By 2030, the goal is to establish Uzbekistan as a regional fintech hub.
One pillar of the strategy envisages an ecosystem that would support fintech companies from the initial idea through to scaling up their business.
It will include an Innovation Hub, a "regulatory sandbox" (a special legal regime in which financial technology firms can test new products and services in a controlled environment), a talent training system, and mechanisms for financing and for cooperation between banks and fintech firms. Startups are expected to progress through incubation, testing in a regulated environment, licensing and, later, expansion.
The presentation also cites plans, previously announced by the president, to set up a Fintech Office and an Innovation Hub under the central bank, drawing on specialists from Singapore.
The central bank plans to prepare 20-30 fintech startups each year to enter foreign markets and to create conditions for attracting up to $1 billion in investment into the sector by 2030.
Open banking and digital ID
A separate section of the strategy focuses on building digital finance infrastructure.
Authorities plan to develop open banking and open application programming interfaces (APIs), enabling financial institutions and other market participants to exchange data securely with customers' consent. This is expected to foster new business models, stronger competition and the growth of financial services.
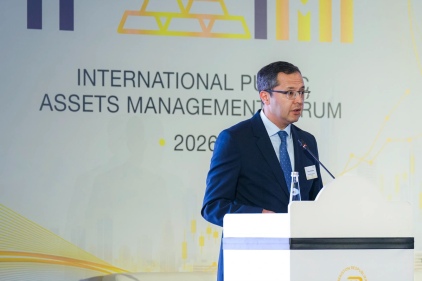
"When we announced open banking, we wanted fintech companies to be able to enter the traditional banking market, perhaps offering just one of the products banks usually provide. But they can do it so efficiently that, ultimately, they will drive competition and innovation," central bank Governor Timur Ishmetov has said.
The strategy also calls for improving the digital identification system to allow customers to be verified remotely, prevent fraud and make financial services easier to access.
Pilot projects using digital ID are due to begin in 2026-2027, with the infrastructure to be extended across the entire financial sector in 2028-2029.
Digital assets and artificial intelligence
The strategy allows for controlled experiments with the tokenization of real-world assets, including securities, as well as testing of how different financial services work together.
The central bank also intends to identify priority areas for the use of artificial intelligence in finance and to launch pilot projects.
AI is also expected to be used in supervision, notably to detect financial crime. The strategy provides for the development of SupTech (supervisory technology), automated data collection via APIs, monitoring of operational incidents and tighter oversight of financial institutions' cybersecurity.
Central bank digital currency and cross-border payments
One proposal concerns regional financial integration. Among the initiatives listed in the presentation is a wholesale central bank digital currency (wCBDC).
It is being considered alongside the development of interconnected regional payment systems, simpler cross-border transactions and lower remittance costs.
The plan also calls for greater transparency on fees and exchange rates in international transfers and for the development of digital trade finance tools.
In 2028-2029, the central bank expects to launch initiatives to integrate regional payment systems, along with cross-border pilot projects.
Uzbekistan seeks to become a regional fintech hub
Another strand of the strategy is attracting foreign fintech companies and investment.
To that end, authorities plan to draw on the Innovation Hub, the Enterprise Uzbekistan project and the Tashkent International Financial Center, hold the Silk Road Finance & Technology Forum, and develop cooperation with fintech hubs abroad.
By 2030, the government aims to turn Uzbekistan into a regional center for fintech investment and innovation, expand the presence of international companies and deepen financial integration in Central Asia.
Consumer protection and fraud prevention
The strategy provides not only for developing new financial services but also for stronger protection of customers.
Plans include a coordinated anti-fraud system across the financial sector, greater transparency in credit products, an improved credit information system and better financial literacy among the population.
Regulation is to become risk-based, with requirements for market participants varying by the scale and risk level of their activities. Authorities also plan to step up oversight of compliance with consumer rights and of how clearly financial institutions disclose the terms of their services.
What the central bank sees as the market's problems
In the presentation, the central bank identifies several problems the strategy is meant to address. They include the limited reach of international remittances, insufficient access to financing for small and medium-sized businesses, gaps in access to financial services between population groups, growing risks for users of digital services and the need for long-term financing.
According to the presentation, 94% of Uzbekistan's population uses the internet, about 72% use digital payments, and the number of remote banking users has risen by almost 70%.
Among the key expected outcomes, the central bank lists growth in the number of fintech companies and in foreign investment, expanded financing for small and medium-sized businesses, wider access to and greater safety of digital finance, the development of cross-border payment infrastructure and stronger regional integration.